

Most TASE indices are total return indices. Dividend yields are included in the indices and are reflected in their rate of return. No special adjustments are made by TASE to reflect the dividend yield in the total return; rather the indices' construction as total return indices is a natural outcome of the system of calculating ex-dividend share prices.
In other stock exchanges it is not customary to adjust share prices for dividend distributions, and for this reason most major indices published worldwide are price indices rather than total return indices. In most cases, total return indices, which reflect dividend yields, are calculated alongside the major indices. Indices are published with an accuracy of two decimal places.
The following formula is used to calculate tracking indices:
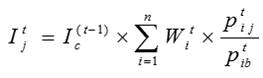
The following formula is used to calculate price index:
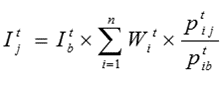
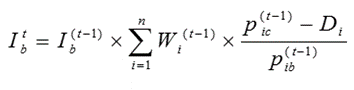
Index Parameters:
|
Parameter |
Explanation |
|---|---|
|
It j |
Index in day t in point of time j |
|
I(t-1)c |
Closing index in day (t-1) |
|
n |
Number of shares included in the index |
|
Wit |
Weight of share I in the index in day t |
|
Ptij |
Share price of I in day t in point of time j |
|
Ptib |
Base price of share I in day t |
|
Itb |
Index base price in day t |
|
I(t-1)b |
Index base price in day t-1 |
|
Wi(t-1) |
Index's weight of share I in day t-1 |
|
P(t-1)ic |
Closing price of share I in day t-1 |
|
P(t-1)ib |
Base price of share I in day t-1 |
|
Di |
Ex-dividend trading day in share I – Gross dividend in Agorot paid in share i. |

